Data-center construction spending has surged above $68 billion annually...
That's already well above the roughly $53 billion being spent on warehouses and $56 billion on healthcare facilities... and nearly 50% higher than a year ago.
Cooling business nVent Electric (NVT) is racing to capture that spending... and is on its way to becoming a one-stop shop for data centers.
The company recently agreed to acquire power-distribution specialist Maverick Power for about $1.8 billion now... and up to another $550 million later on.
The deal expands nVent into switchgear, control panels, and other power-distribution equipment. It follows last year's $975 million acquisition of Avail Infrastructure Solutions' electrical-products business.
At this point, nVent is tackling nearly all things data center. But even as the AI build-out continues, that doesn't guarantee it's going to be a great stock.
NVent is already one of the largest established suppliers of liquid-cooling systems...
Those systems are becoming increasingly important as advanced AI chips generate more heat and, thus, need more cooling.
But the Maverick acquisition has added another tier to nVent's offerings by giving it greater exposure to the equipment that distributes electricity throughout a data center.
NVent enters this expansion from a position of strength...
Its Uniform return on assets ("ROA") has stayed around 30% for five straight years. That's exceptional profitability for an industrial company. And it shows that nVent already knows how to earn strong returns from its asset base.
The near-term outlook is even stronger...
Analyst expectations in the Uniform Accounting framework call for Uniform ROA to reach roughly 44% in 2026. That would push profitability toward the highest levels nVent has ever generated.
There is a solid fundamental reason for that optimism, but the market is setting a much higher hurdle...
We can see this through our Embedded Expectations Analysis ("EEA") framework.
The EEA starts by looking at a company's current stock price. From there, we can calculate what the market expects from the company's future cash flows. We then compare that with our own cash-flow projections.
In short, it tells us how well a company has to perform in the future to be worth what the market is paying for it today.
For nVent, that framework shows investors already expect profitability to rise far beyond the company's recent performance.
At today's prices, the market is pricing in Uniform ROA climbing to approximately 62% by 2030.
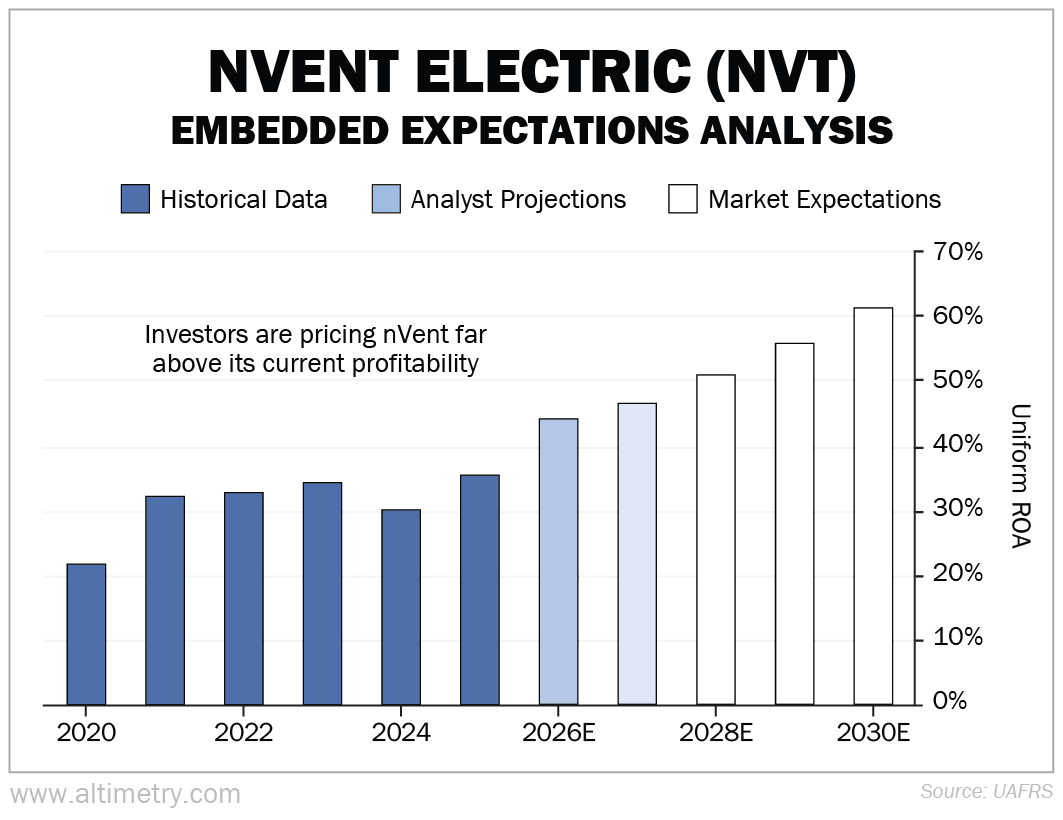
Even if nVent hits what analysts expect over the coming two years, it's still a far cry from what the market is pricing in today for 2030.
The Maverick acquisition expands nVent's exposure to AI infrastructure. But it also raises the amount of money it's spending. Remember, nVent is spending as much as $2.3 billion for Maverick, after already committing nearly $1 billion to acquiring Avail.
Those investments can strengthen nVent's competitive position... but they have to generate extraordinary returns if the company is going to reach the profitability embedded in today's share price.
Investors demand much more than strong growth...
NVent has many qualities investors want from an AI-infrastructure company.
It already earns strong returns... well above the corporate average.
And it has meaningful exposure to one of the biggest bottlenecks in AI: liquid cooling. And with its recent acquisition spree, it's exposed to even more of the data-center market.
But today, shareholders are paying as though a large portion of the opportunity has already been captured. NVent can keep gaining share and improving profitability... but still fall short of the market's ambitious expectations for it.
The company doesn't need to lose the AI-infrastructure race for investors to be disappointed. Even if its execution is excellent... investors don't want anything short of extraordinary.
NVent looks like a great AI-infrastructure business... just at the wrong price.
Regards,
Joel Litman
September 16, 2026