Toymaker Mattel (MAT) just had its best day in more than seven years...
Last Thursday, the Wall Street Journal reported that brand-licensing giant Authentic Brands had approached Mattel about a takeover.
You likely know the name Mattel – it's known for iconic toy brands like Barbie, Hot Wheels, and American Girl.
Authentic's offer values Mattel at about $6 billion, or more than $20 a share. (It's important to note this offer is not formal and is still being privately discussed.)
Authentic owns famous brand names and licenses them to companies that make and sell the actual products. It built its empire on clothing labels like Reebok and Champion. And it recently struck a $1.4 billion deal to take jeans maker Guess private.
Mattel shares jumped 19% on the news of the proposed deal. That's the stock's biggest one-day gain since February 8, 2019, when shares soared roughly 23%.
Even so, the stock is still down nearly 20% this year. And it's far from certain that the deal will happen. Mattel isn't running a formal sale process (where a company actively shops itself to bidders), and a brand-new CEO is about to take over.
But as we'll explain today, Wall Street has set the bar so low for Mattel that the stock is worth a look... whether or not the Authentic deal pans out.
Mattel has given investors plenty of reasons to sell this year...
Early this year, management surprised investors with an extra $150 million in 2026 spending on new projects like mobile games. That was about 15% of its yearly cash earnings, and it was a big reason the company's profit forecast for the year came in well below Wall Street's expectations.
Then last Wednesday, longtime CEO Ynon Kreiz said he was leaving to become co-CEO of newly formed media giant Skydance (SKYD). Roger Lynch, the head of magazine publisher Condé Nast, will replace him on November 2.
But despite these obstacles, Mattel is holding up better than the share price suggests.
Mattel's profitability has held up...
We measure profitability with Uniform return on assets ("ROA"). It strips out the accounting distortions that make companies hard to compare.
Mattel's Uniform ROA has hovered between 9% and 14% over the past four years. Analysts expect this range to hold, predicting 12% this year and 11% next year.
We can see this through our Embedded Expectations Analysis ("EEA") framework...
The EEA starts by looking at a company's current stock price. From there, we can calculate what the market expects from the company's future cash flows. We then compare that with our own cash-flow projections.
In short, it tells us how well a company has to perform in the future to be worth what the market is paying for it today.
Even after the recent rally, the market expects Mattel's Uniform ROA to slide to 8% by 2030. That would be its worst level since 2020. Take a look...
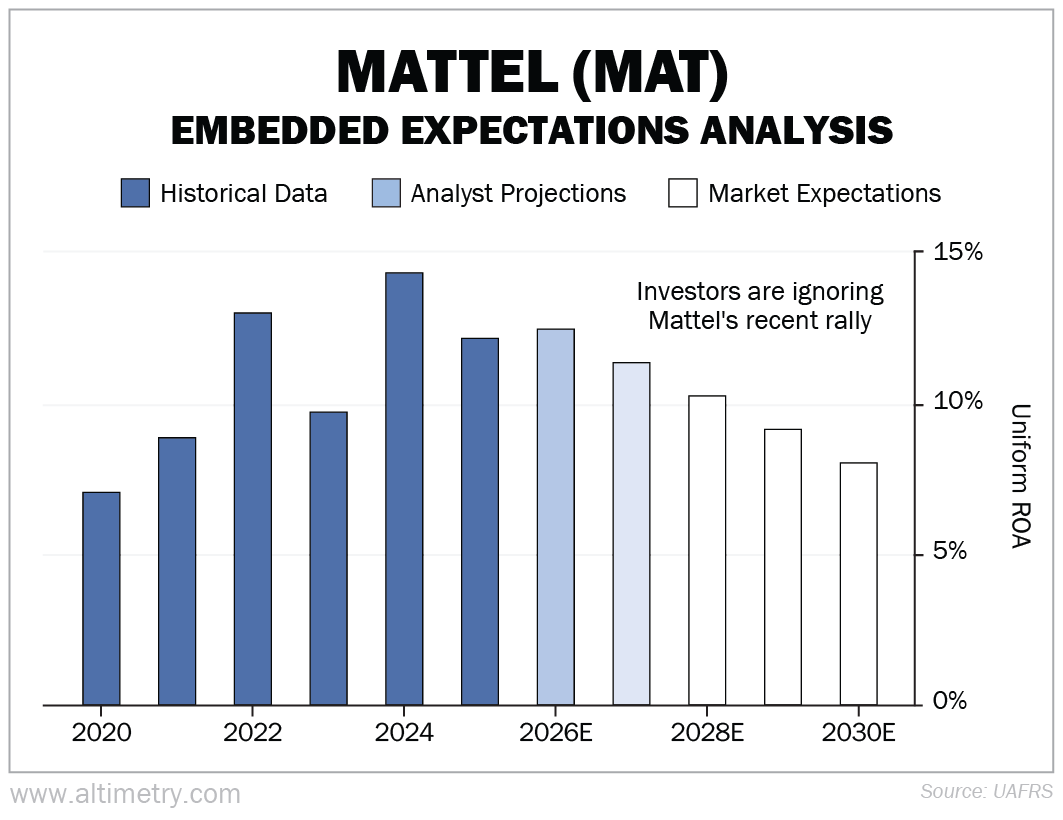
In other words, investors are betting that Mattel's returns will shrink every year for the next four years... even though analysts expect them to hold near today's levels.
That's why Authentic is interested...
Its whole strategy is buying well-known brands for less than they're worth. And few toy brands rival those under Mattel's umbrella.
Even at $20 a share, Authentic would be paying for a Uniform ROA of about 9% by 2030. That's still right around Mattel's five-year low.
So Authentic could pay a premium of roughly 25%, or even more, and still get Mattel at a bargain.
You don't need a takeover to profit from that gap...
Buyout talks fall apart all the time. Mattel's new CEO may want to try his own plan first... Or Authentic might never even make a formal offer.
So don't buy Mattel for the potential deal... Buy it for the low bar.
If Mattel keeps its returns where they've been for the past four years, it'll beat what the market is pricing in. A deal at $20-plus per share would just be a bonus.
Authentic Brands found the bargain first. But it's not too late to buy in.
Regards,
Joel Litman
October 8, 2026