Dutch semiconductor-equipment maker ASML (ASML) raised its sales outlook again...
In its third-quarter earnings call last month, it raised the low end of its 2026 sales outlook to 44 billion euros, up from 43 billion euros. That's the third time it has lifted its forecast this year.
As we discussed in August, the last outlook adjustment was already well above Wall Street's estimates.
ASML is a particularly strong beneficiary of the ongoing AI boom. It's the only company that makes the extreme ultraviolet ("EUV") machines needed for advanced AI chips. These machines use light to print circuit patterns thousands of times thinner than a human hair.
And ASML can't build enough of them. Management warned that it won't fully meet demand in 2027 and 2028... And some customers already want to place orders for 2029 and 2030.
However, investors still have doubts. The same week as ASML's earnings call, chip and software giant Broadcom's (AVGO) CEO, Hock Tan, compared chip investors with gamblers at a casino... And chip stocks sold off around the world as a result.
As we'll explain today, the market is expecting ASML's earnings growth to slow sharply after 2027... right when its new prices kick in.
When demand outruns supply, the seller sets the price...
"Customers are asking us every single day to get more tools," ASML CEO Christophe Fouquet said in a video released with the company's third-quarter results.
Back in July, ASML said it would boost capacity for its EUV machine by 30% next year, to about 85 units. Now, it's already looking for ways to go beyond that for 2028.
But ASML can't just flip a switch. Its own suppliers are stretched thin. And another major campus in the Netherlands won't finish its first phase of construction until 2029.
ASML Chief Financial Officer Roger Dassen told reporters it would be hard to add a huge amount of capacity by 2028, even if the company started today.
So instead, ASML is charging more. A single EUV tool can already cost as much as $400 million. And ASML has secured price hikes from its biggest customers.
These higher prices will start showing up next year and take full effect in 2028.
Profitability is already moving... Gross margin rose to 57.5% in the third quarter, up from 54% the previous quarter.
Analysts expect earnings to more than double...
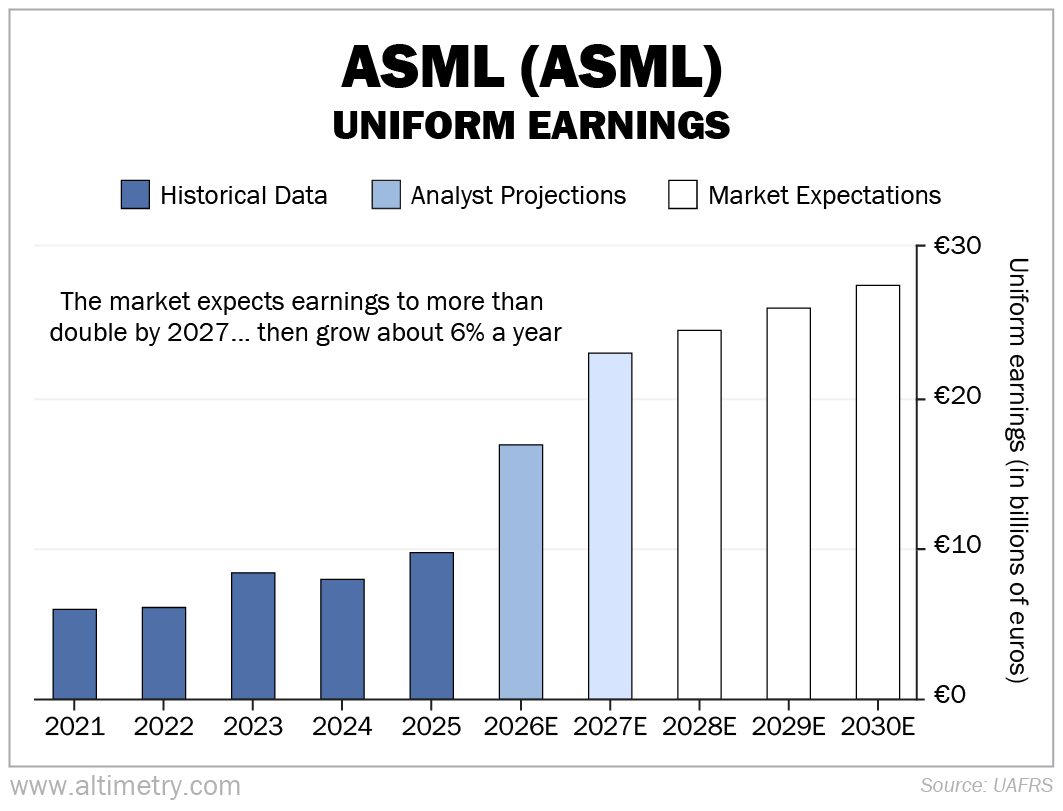
We measure profits with Uniform earnings, which strip out the distortions in as-reported accounting. ASML's Uniform earnings grew from 6 billion euros in 2021 to 9.8 billion euros in 2025. That's growth of about 13% a year.
With the impending price hikes, analysts expect even faster growth now. They see Uniform earnings reaching 17 billion euros this year and 23 billion euros in 2027. That's more than double 2025's Uniform earnings... and that only accounts for some of the price increases.
But the market is betting the AI boom will end in 2027...
We can see this through our Embedded Expectations Analysis ("EEA") framework.
The EEA starts by looking at a company's current stock price. From there, we can calculate what the market expects from the company's future cash flows. We then compare that with our own cash-flow projections.
In short, it tells us how well a company has to perform in the future to be worth what the market is paying for it today.
Investors already expect ASML's Uniform earnings to more than double by 2027. Their doubts start after that...
Based on today's stock price, investors are only expecting ASML's Uniform earnings to reach roughly 27.5 billion euros by 2030.
That's growth of about 6% a year after 2027... less than half the pace ASML managed from 2021 to 2025.
Take a look...
In other words, the market buys the AI surge... but only through the end of next year. It's betting that ASML's growth will slow right as its higher prices kick in.
ASML doesn't need a miracle to clear this bar...
ASML is sold out through 2028. Its new prices are locked in. And customers are already lining up for 2029 and 2030.
Now, there are risks. U.S. lawmakers want new limits on chip-equipment sales to China, which are expected to make up about 20% of ASML's revenue this year.
But beating 6% growth a year won't take a new AI boom. It will only take the prices and capacity ASML has already announced.
That's why ASML remains in our Hidden Alpha portfolio. We first recommended it in February 2025, when we argued AI would keep its returns climbing. Since then, the stock has more than doubled.
ASML is still a buy up to $2,000 per share in Hidden Alpha. If chip-stock jitters knock its shares down, treat the dip as a chance to buy.
The market is pricing in a slowdown. ASML's order book says otherwise.
Regards,
Joel Litman
November 6, 2026
P.S. If you're interested in learning more about my Hidden Alpha newsletter – where I uncover overlooked opportunities in well-known, large-cap stocks – click here.